All Categories
Featured
Understanding Indexed Universal Life IUL Policies for Retirement
Table of Contents
1 Rates are based upon the average month-to-month premium for Georgia Direct Premium rates market Class A; Aflac Term Life Insurance TERM LIFE POLICY - Series 860000; Premiums may differ by protection type, account, state of issue, and the election of additional/optional advantages. 2 NerdWallet - Typical Life Insurance Rates in 2026.
. Accessed April 14, 2026. Content within this article is supplied for basic educational functions and is not supplied as tax, legal, health, or financial recommendations for anybody or for any particular scenario. Companies, workers, and other people must call their own advisers about their circumstances. For complete details, consisting of availability and costs of Aflac insurance, please contact your regional Aflac agent/producer.
In Delaware, Policies A68200, A68300 & A68400. Whole Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400.
Essential Expense and Burial Insurance Options
Not offered in Delaware, Idaho, New Mexico, New York, Oregon or Vermont. B61000, Juvenile series: In Arkansas, Idaho, Oklahoma, Oregon, Pennsylvania, Texas & Virginia, Policies: ICC18B61JWO & ICC18B61JTO. In Delaware, Policies B61JWO & B61JTO. Q60000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Pennsylvania & Texas, Policy ICC18Q60200M. In Delaware, Policy Q60200M.

Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK. In New York City, Policy: NYQ60100M. Not offered in VA. Receipt of accelerated death advantages might affect eligibility for public assistance programs. Advantages might also be taxable, and are not anticipated to get the very same beneficial tax treatment as other types of sped up survivor benefit that might be offered.
Policies and riders might also consist of a waiting period. Refer to the exact policy and rider types for benefit details, meanings, constraints and exemptions. Premiums are guaranteed by CMFG Life Insurance Business.
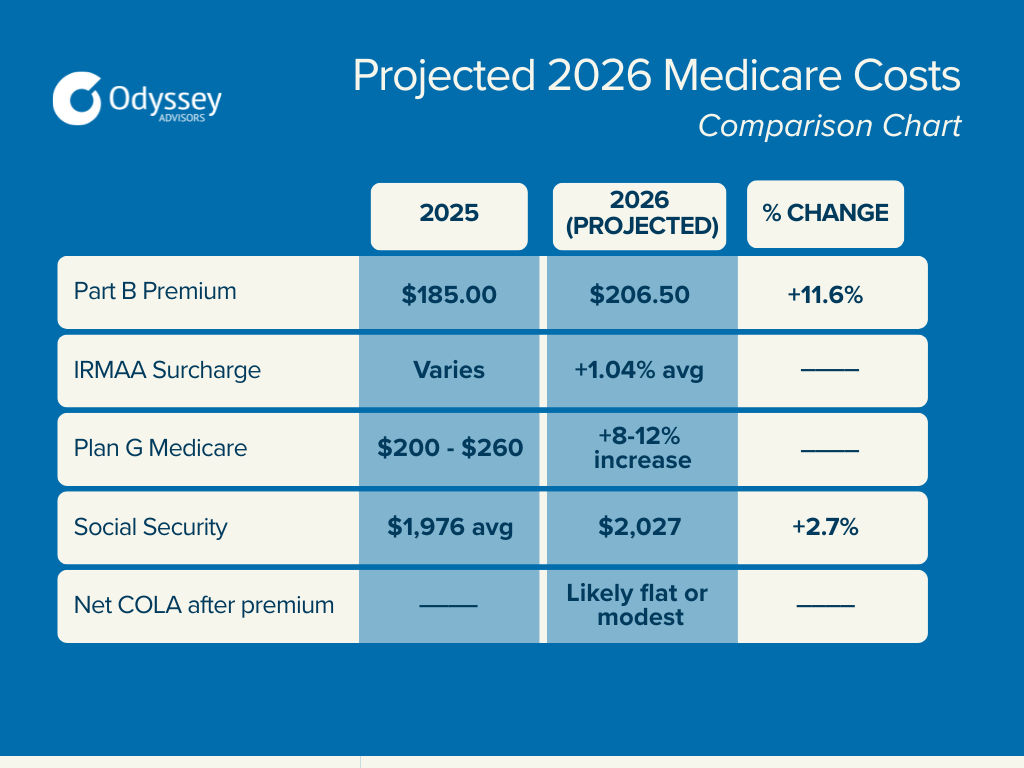
Direct Consumer Advice for Selecting 2026 Medicare Plans
* Based on your health and other elements affecting your insurability, you might be denied protection. Mon. Fri. 7 am9 pm; Sat. 8 am4 pm(CST)Your approval for this item is based upon your responses to the questions on the application and information we obtain from other sources. Please see your policy or call us for information. The insurance provided is not a deposit, and is not federally insured, sold or guaranteed. Product and features may not be available in all states. Lots of people are waiting up until later on in life to begin families. If you're one of them and you postpone purchasing life insurance till you have children, it might cost you the opportunity of securing a low premium. Even if you do not yet have children to safeguard, life insurance can cover your individual financial obligations, medical expenses, home mortgage, lost earnings, and even funeral expenditures. Your health status is one of the most essential aspects when figuring out term life insurance rates.
The healthier you are, the less you pay, so getting life insurance at a younger age can be advantageous. As you age, the threat of establishing health concerns(such as cancer or diabetes)boost, and can result in higher premiums and sometimes even make it challenging to get protection. Here is a complete rate breakdown demonstrating how premiums increase years by decade.
AgeMonthly PremiumAnnual CostTotal Over 20 Years25$18$216 $4,32030 $21$252 $5,04035$26 $312$6,24040$36$432$8,64045$55$660$13,20050$85$1,020$20,40055$135$1,620$32,40060$215$2,580$51,600 AgeMonthly PremiumAnnual Cost25 $15$18030$ 18$21635$22$26440$30$36045$45$54050$68$81655$108$1,29660$175$2,100 Rates are price quotes. Real premiums depend upon health, carrier, and state. The difference between buying at 30 vs. 50 is $64/month or $15,360 over twenty years for the very same protection.
Here is a 20-year level term rate chart throughout $250K, $500K, and $1M (male, Preferred Non-Smoker): Age$250,000$500,000$1,000,00030$14$21$3840$23$36$6550$52$85$15660$128$215$395 Doubling your coverage does double your premium a set policy cost is spread throughout more protection, so $1M is normally far less than 2 the $250K rate. If you are picking in between amounts, buying more protection while young is often the much better worth.
Smokers typically pay the non-smoker premium at the very same age. The majority of carriers move you to non-smoker rates after tobacco-free, so quitting before you use can cut your premium roughly in half.

Latest Posts

Maximizing IUL Growth Strategies
Understanding Indexed Universal Life IUL Policies for Retirement
Securing Coverage to Support Seniors